Manufacturing's Future Depends on Companies Most Americans Don’t Know
Some of the greatest names in the annals of American business are manufacturers: from General Motors, General Electric and General Mills to Caterpillar, Lockheed Martin and Boeing; from John Deere, Ford Motor Co. and Kraft Heinz to Tesla, Coca-Cola and Procter & Gamble.
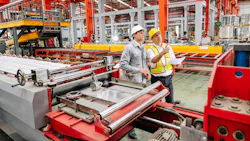
All iconic brands. And yet, while they built American manufacturing’s reputation around the world, the backbone of our factory sector has always rested with a different group of companies—the “industrial middle,” a group of primarily B2B manufacturers, ranging from roughly $30 million to $10 billion (using RSM’s definition), most of whose names are barely known by American consumers. We’re talking makers of precision machined components, metal fabrications and castings and forgings. Electronic assemblies, industrial automation systems and specialty chemicals. Packaging equipment, industrial software and controls, and tooling and molds.
The cars we drive and airplanes we fly, the electronics we use and the electrical grid we rely on, the groceries that sustain us and packaged foods that nurture us, the homes and offices we live and work in—they wouldn’t exist without this American industrial core.
In tribute to these companies, here are four important reasons why the B2B middle reflects the past, present and future of American manufacturing.
Anchoring Domestic Supply Chains
Without the nation’s mid-size processors, component makers, tool-and-die shops and suppliers, U.S. factories would have to rely on foreign sources—which would pose a significant risk to American supply chains, as the 2020-21 crisis readily demonstrated. Countering the old trope (resurrected in recent years by President Donald Trump) that we don’t make anything here anymore, roughly 70% of the intermediate inputs U.S. manufacturers use are sourced domestically, and a large share of that comes from mid-size suppliers. Food and beverage firms rely overwhelmingly on domestic agriculture and processing; chemical manufacturers rely on U.S.-sourced chemical components, resins and feedstocks; and primary and fabricated metals are dependent on U.S. steel mills and metal fabricators. American B2B manufacturers are essential to keeping our factories running.
Bridging Innovation and Commercial Scale
Economists recognize that startups are excellent at inventing things and large companies are great at scaling proven technologies. But they also know it’s the mid-size manufacturers that often bridge the gap, industrializing solutions for startup innovations and piloting new technologies for OEMs. One key reason: These mid-size industrials not only employ a significant portion of the engineers who improve manufacturing processes, they consistently invest in application-specific R&D. Using National Science Foundation data, we can extrapolate that upwards of $150 billion—or about 37% of annual manufacturing R&D spending—comes from this the industrial middle.
Sustaining Regional Economies
Fifteen years ago, Harvard’s Willy Shih and Gary Pisano issued their groundbreaking book “Producing Prosperity,” which highlighted the critical importance of “industrial commons”—localized webs of specialized suppliers, skilled tradespeople, R&D labs and educational institutions that have made U.S. manufacturing innovation possible and that stimulate economic prosperity in those regions. (This came two decades after Michael Porter introduced the broader concept of “business clusters,” geographic concentrations of interconnected companies in a specific region.)
While larger manufacturers—think Boeing in Seattle—are the hub of some key U.S. innovation clusters, dozens of other manufacturing-centric regions have more moderately sized operational anchors. For instance, Northeast Ohio has an advanced manufacturing cluster centered around multiple industrial companies like Lincoln Electric, Swagelok and Nordson. They are surrounded by a dense supplier network of hundreds of companies, and work in collaboration with Case Western Reserve University. Wisconsin has a vibrant industrial equipment cluster featuring companies like Rockwell Automation, Oshkosh Corporation and Generac, who collaborate with the University of Wisconsin system and the Milwaukee School of Engineering. And South Carolina is home to an advanced materials and industrial manufacturing hub, centered around Milliken & Company, Sonoco Products and Ingevity, which spend significant amounts on applied R&D.
Without all these mid-size manufacturers and thousands of others, those regional economies would stagnate.
Maintaining and Developing Our Domestic Infrastructure
Companies in the industrial middle are essential to the maintenance and improvement of our infrastructure. Think of all the inputs—from voltage control to conductors and line hardware, from chemical additives and steel and metal products to heavy machinery and equipment—that are needed for a vast U.S. energy sector that generates an estimated 96 quadrillion Btu each year. The iron pipes and fittings, fire hydrants, pipe-joining couplings and wastewater pumps required for our approximately 152,000 public drinking water systems and 17,000 wastewater treatment systems. The construction aggregates, asphalt, gravel, rebar and Portland cement used in the 4.2 million miles of public roads and more than 600,000 bridges.
The companies behind these intermediate inputs are for the most part unknown to the typical American consumer. Yet these behind-the-scenes mid-size manufacturers are at the very core of our domestic infrastructure.
The industrial middle is the connective tissue of American manufacturing: the supplier behind the supplier, the shop that turns a prototype into a product, the employer that keeps a regional economy running. For leaders across the sector, that means treating mid-size manufacturers as strategic partners, not interchangeable vendors. For policymakers, it means measuring this segment on its own terms and designing public policy that strengthens it rather than overlooks it.
The companies the public doesn’t know are the ones the country can’t do without.
About the Author
 Stephen Gold
President and Chief Executive Officer, Manufacturers Alliance
Stephen Gold is president and CEO of Manufacturers Alliance. Previously, Gold served as senior vice president of operations for the National Electrical Manufacturers Association (NEMA) where he provided management oversight of the trade association’s 50 business units, member recruitment and retention, international operations, business development, and meeting planning. In addition, he was the staff lead for the Board-level Section Affairs Committee and Strategic Initiatives Committee.
Gold has an extensive background in business-related organizations and has represented U.S. manufacturers for much of his career. Prior to his work at NEMA, Gold spent five years at the National Association of Manufacturers (NAM), serving as vice president of allied associations and executive director of the Council of Manufacturing Associations. During his tenure he helped launch NAM’s Campaign for the Future of U.S. Manufacturing and served as executive director of the Coalition for the Future of U.S. Manufacturing.
Before joining NAM, Gold practiced law in Washington, D.C., at the former firm of Collier Shannon Scott, where he specialized in regulatory law, working in the consumer product safety practice group and on energy and environmental issues in the government relations practice group.
Gold has also served as associate director/communications director at the Tax Foundation in Washington and as director of public policy at Citizens for a Sound Economy, a free-market advocacy group. He began his career in Washington as a lobbyist for the Grocery Manufacturers of America and in the 1980s served in the communications department of Chief Justice Warren Burger’s Commission on the Bicentennial of the U.S. Constitution.
Gold holds a Juris Doctor (cum laude) from George Mason University School of Law, a master of arts degree in history from George Washington University, and a bachelor of science degree (magna cum laude) in history from Arizona State University. He is a Certified Association Executive (CAE).